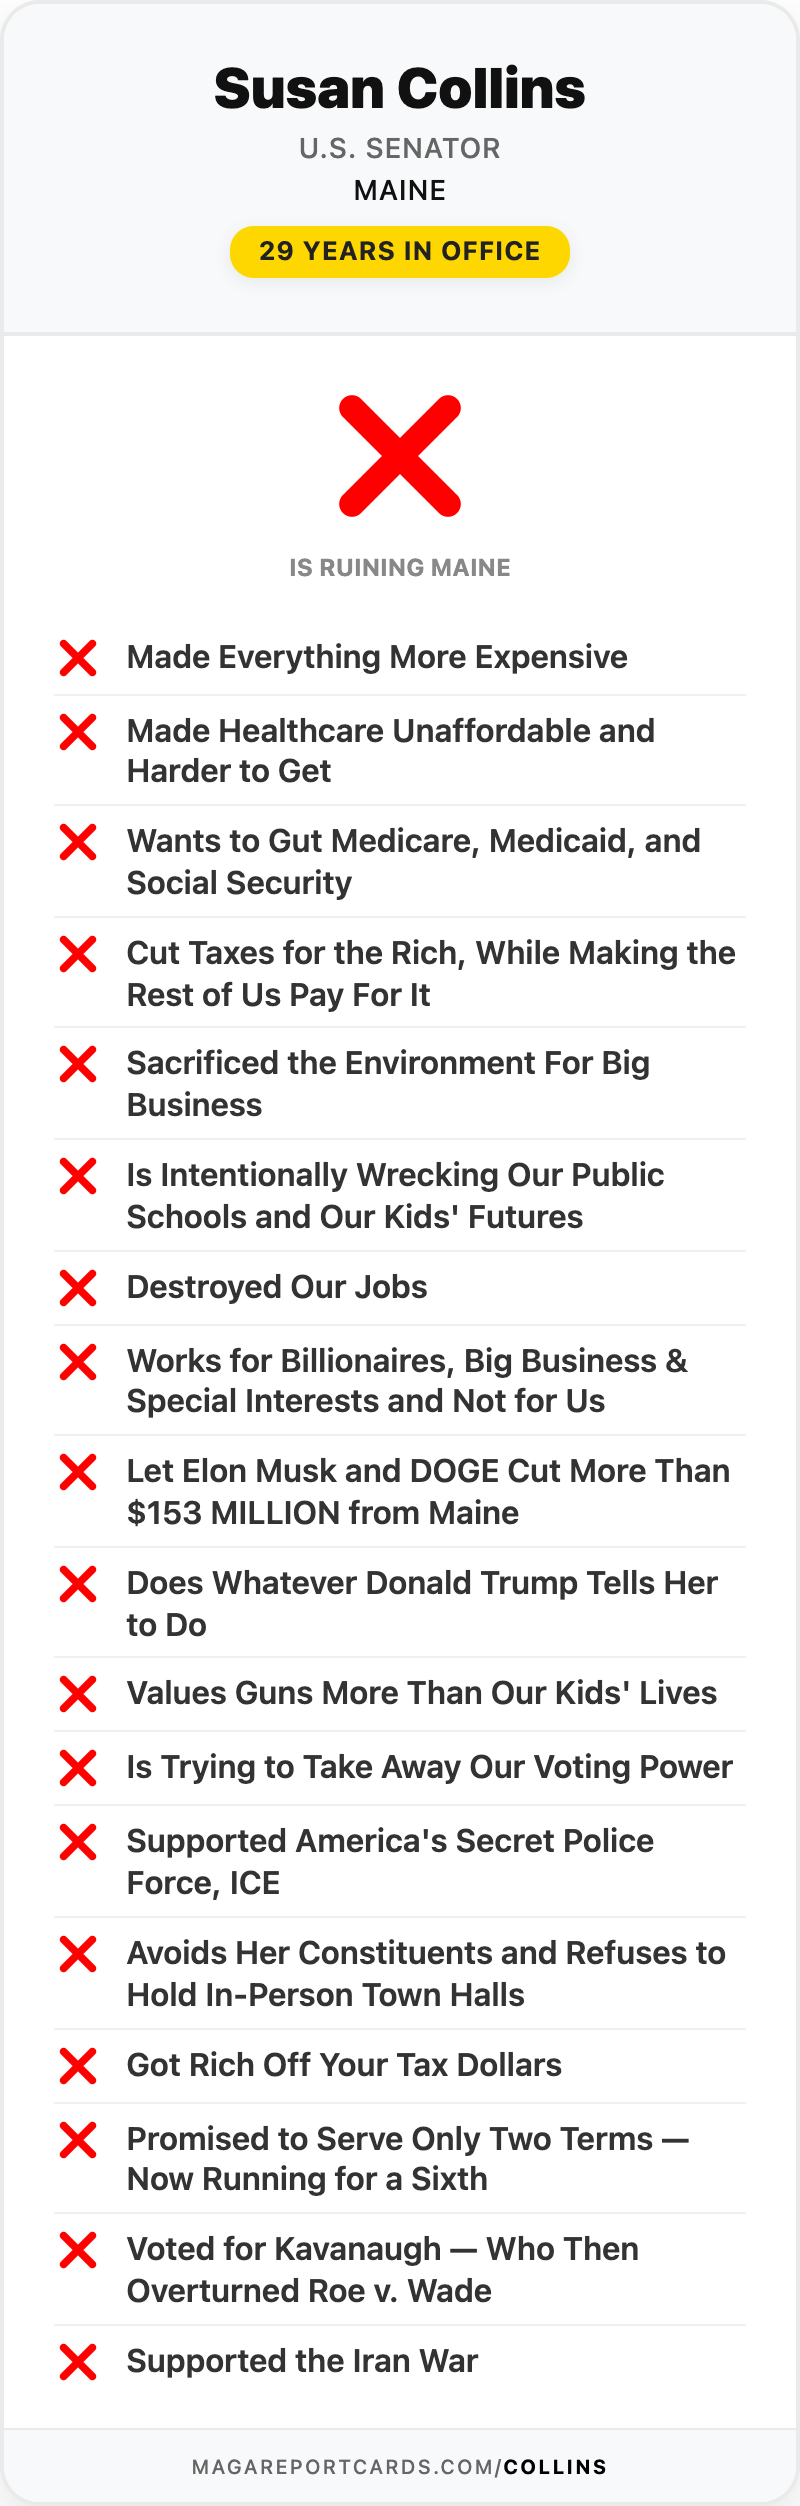
Susan Collins has found an attack she likes against Troy Jackson, her Democratic opponent: he called two different houses his home.
At their October 6 debate, she went after a federally backed mortgage on a house Jackson owned in Augusta, which listed it as his primary home while he represented Allagash in the Maine Senate.
"How can he have a primary residence in Allagash for which he was reimbursed $160,000 for travel back and forth, and have a primary residence in Augusta?"
It's a fair question to ask a politician. So the Bangor Daily News asked it about Collins. Her own mortgage records give the answer she'd rather not hear.
Two "principal residences" at the same time
When you take out a standard mortgage on a home you'll live in, you sign a pledge: you'll live there as your principal residence for at least a year, unless the lender agrees otherwise in writing. Lenders often charge less on those loans, because they see them as less risky.
Here's what Collins signed, according to the records the BDN reviewed:
- 2000: Collins bought a rowhouse on Capitol Hill in Washington. Her Bank of America mortgage listed her address as Bangor, but it required her to live primarily in the Washington house.
- 2004: She refinanced the Washington rowhouse. In all, she twice signed mortgage documents pledging to use it as her principal residence.
- Four months later, still in 2004: She told a Bangor bank that a new house in Bangor would be her principal residence, while her Washington pledge was still in effect.
That left Collins bound by two mortgages, each naming a different house as her principal residence, for about eight months. Meanwhile, Bangor is where she has claimed Maine's homestead exemption.
Jackson was not in that position. The one-year pledge on his Allagash mortgage had expired in 2016, before he bought the Augusta house. Collins, by the BDN's account, held two live pledges at once.
To be clear about what the records show: the BDN says they do not show that Collins broke the law. What they show is that she made the same kind of pledge she is now attacking Jackson for, and then went a step further.
The questions her campaign wouldn't answer
The two-pledge setup matters for two reasons, and the BDN asked Collins about both.
Did she get a cheaper loan? Mortgages on a home the buyer lives in can carry lower rates. The BDN asked whether Collins's loans were priced as primary-residence mortgages. Her campaign did not directly answer.
Did she take a tax break? A single homeowner can avoid federal taxes on up to $250,000 of profit from selling a primary residence, but only one home can be your primary residence at a time. Collins sold the Washington rowhouse in November 2010 for $511,000, after buying it for $240,000. The BDN asked whether she claimed that break. Again, no direct answer.
Collins's campaign didn't hand over her tax records or a letter from her accountant when the BDN asked. Jackson's campaign did: his accountant wrote that he did not claim the home-sale tax break when he sold the Augusta house in 2021.
So in this fight over mortgages, the one being accused showed his paperwork. The one doing the accusing didn't.
Her campaign's defense doesn't hold up
Collins's spokesperson, Blake Kernen, said Jackson's case was different because his loan was backed by the Federal Housing Administration, which requires a primary residence. Kernen called that program meant for first-time and low-income buyers.
The BDN checked: FHA loans have no income limits and are not restricted to first-time buyers.
Kernen also said Collins "used conventional loans which aren't just meant for primary homes." Conventional loans can cover second homes, but only if the lender attaches a "second home rider." Without one, the borrower's principal-residence pledge stays in place. Collins knows how that works. She used the second-home option on other properties, including an Enfield camp she bought in 2000 and a Capitol Hill townhouse she bought in December 2010. On the rowhouse, she signed the principal-residence pledge.
Kernen said Collins relied on professionals who knew about her Senate job when she signed.
Millions spent on an attack she's open to herself
This isn't a throwaway debate line. The pro-Collins super PAC Pine Tree Results spent nearly $2.4 million running an ad on Jackson's mortgage for more than two months, according to ad-tracker AdImpact. It closes: "Troy Jackson: falsifying documents, ripping off taxpayers, and a bully we can't trust."
Jackson's Augusta home was already the subject of a 2023 complaint to the Maine Ethics Commission. Commissioners voted 5–0 not to investigate.
Pine Tree Results is the same super PAC that took $2 million from a billionaire named in the Epstein files before Collins voted to kill an amendment forcing the files' release.
The facts, in short
Susan Collins and a super PAC backing her have attacked Troy Jackson for a mortgage that listed his Augusta house as his primary home. Mortgage records reviewed by the Bangor Daily News show Collins spent about eight months in 2004 bound by two principal-residence pledges at once, one on a Washington rowhouse and one on a Bangor house. Jackson was not bound by two such pledges at the same time. Collins's campaign would not say whether she got a lower rate or a home-sale tax break from those pledges, and did not provide her tax records.